


- Learn how age affects the relative impact of retirement savings rates and portfolio returns on ending account values
- Understand why older investors may benefit more from increasing contributions than taking additional portfolio risk
- See how consistent savings, compounding and realistic returns can help investors work toward retirement goals
 There are two engines of growth in an investment portfolio: the contributions (savings rate) of the investor and the rate of return generated by the portfolio itself. Which has the greater impact? The answer is based on your age.
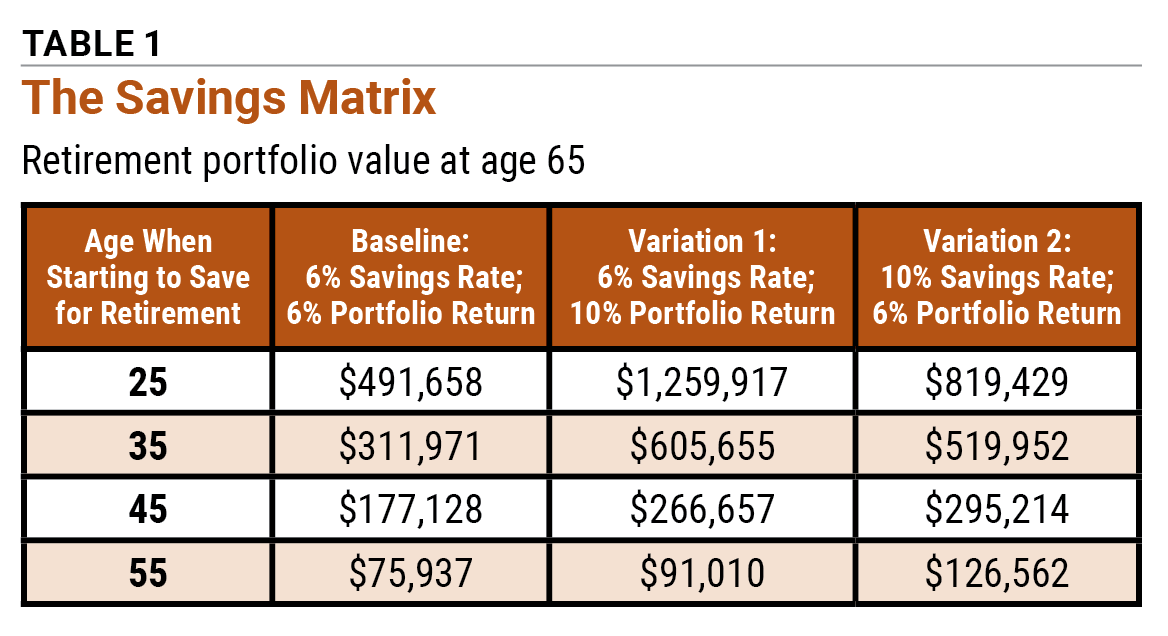
The savings matrix in Table 1 presents various ending account values at age 65. Those amounts are based on four different starting ages. The baseline figures assume a 6% annual savings rate and a 6% annualized rate of portfolio return. The variables in the matrix move from a 6% savings rate to a 10% savings rate or move from a 6% portfolio return to a 10% portfolio return. (In both cases, the other variable is held constant.)
Starting to Save for Retirement at Age 25
For an investor who began putting money into their retirement portfolio at age 25, the baseline terminal portfolio value at age 65 is $491,658, according to the savings matrix. This baseline assumes a $35,000 annual starting salary, 3% annual increases in pay, a 6% savings rate and an annualized portfolio return of 6%. Interestingly, this individual will have earned over $2.63 million during their 40-year working career.
What if the annual portfolio return increases to 10% while the savings rate stays at 6%? The portfolio value at age 65 would be nearly $1.26 million. On the other hand, if the savings rate increases to 10% per year and the return stays at 6% annually, the ending portfolio value at age 65 would be $819,429. Clearly, the portfolio’s rate of return has more impact than the annual savings rate for a young investor based on the ending account value at age 65 (Figure 1).
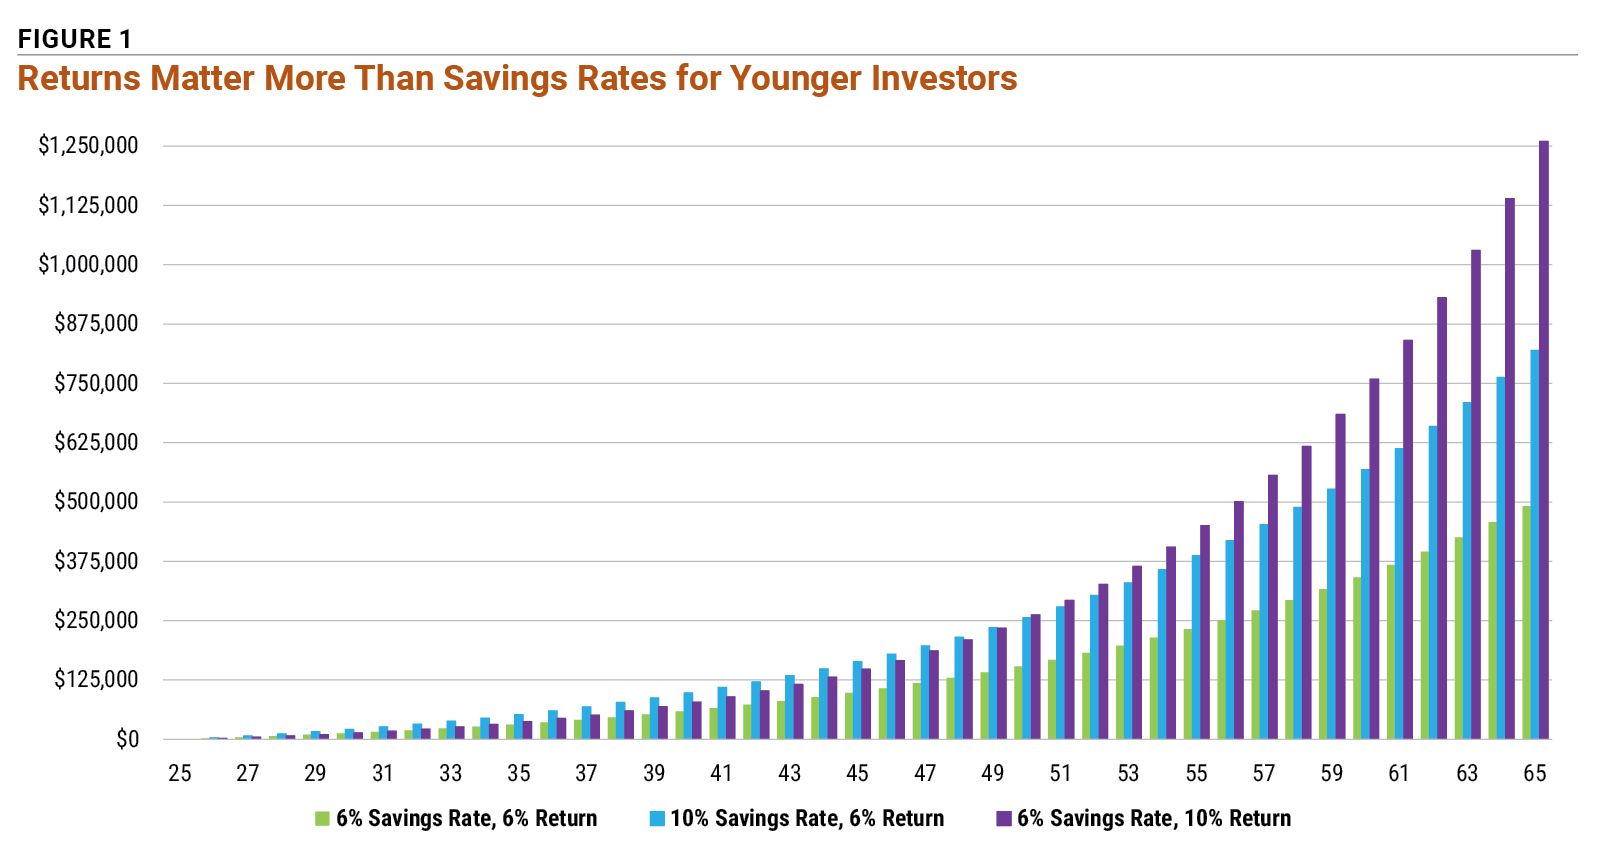
Of course, one might suggest that the best of all worlds for a 25-year-old investor is to save 10% of income each year and have a portfolio return of 10%! There is no question about that, as the ending portfolio value would be an astounding $2,099,861. Again, this assumes a starting annual salary of $35,000 and a 3% annual increase in salary over a 40-year career. While no interruptions in saving or pay raises are factored in, the importance of a high return and time in the market is very clear.
Starting to Save for Retirement at Age 35
Next, we consider a 35-year-old investor. Assuming a 6% savings rate and a 6% annualized portfolio return, the baseline ending portfolio value at age 65 would be $311,971. This person has a starting annual salary of $47,000 with a 3% annual pay increase. (This income figure of $47,000 is simply a 3% annual growth rate applied to the 25-year-old’s $35,000 starting salary for 10 years.) If the portfolio’s annual rate of return increases to 10% (holding the savings rate constant at 6%), the ending account value at age 65 would be $605,655. If the savings rate instead increases to 10% while the annual portfolio return holds steady at 6%, the ending account value would be $519,952.
Once again, increasing the portfolio return from 6% to 10% provides greater impact than increasing the savings rate from 6% to 10% for a “younger” investor.
A 6% or 10% savings rate and a 6% or 10% portfolio return are not the only possible savings rates and rates of return. However, the point of this analysis is to isolate the general impact of altering the savings rate versus changing the portfolio return (by virtue of employing different asset allocation models) at various ages.
Starting to Save for Retirement at Age 45
Things get interesting at age 45. The 45-year-old has a starting annual income of $63,200 and receives 3% annual pay increases until age 65. Using a 6% savings rate combined with a 6% portfolio return results in an ending balance of $177,128 at age 65.
If the savings rate increases to 10% (holding the portfolio return constant at 6%), the ending balance would rise to $295,214. A 6% savings rate with a 10% portfolio return would result in an ending balance of $266,657. We clearly see that increasing the savings rate to 10% at this age has more impact on the ending portfolio balance than increasing the portfolio’s annual rate of return to 10%.
This may seem counterintuitive, as conventional wisdom suggests that a person who is “late” to the retirement planning game needs to make up for lost time by building a largely equity-based portfolio. In other words, they need to allocate aggressively to a portfolio that can crank out returns of 10% to 12% per year.
My analysis suggests otherwise. In fact, the older investor needs to save more each year rather than build an overly aggressive, high-risk/high-return portfolio.
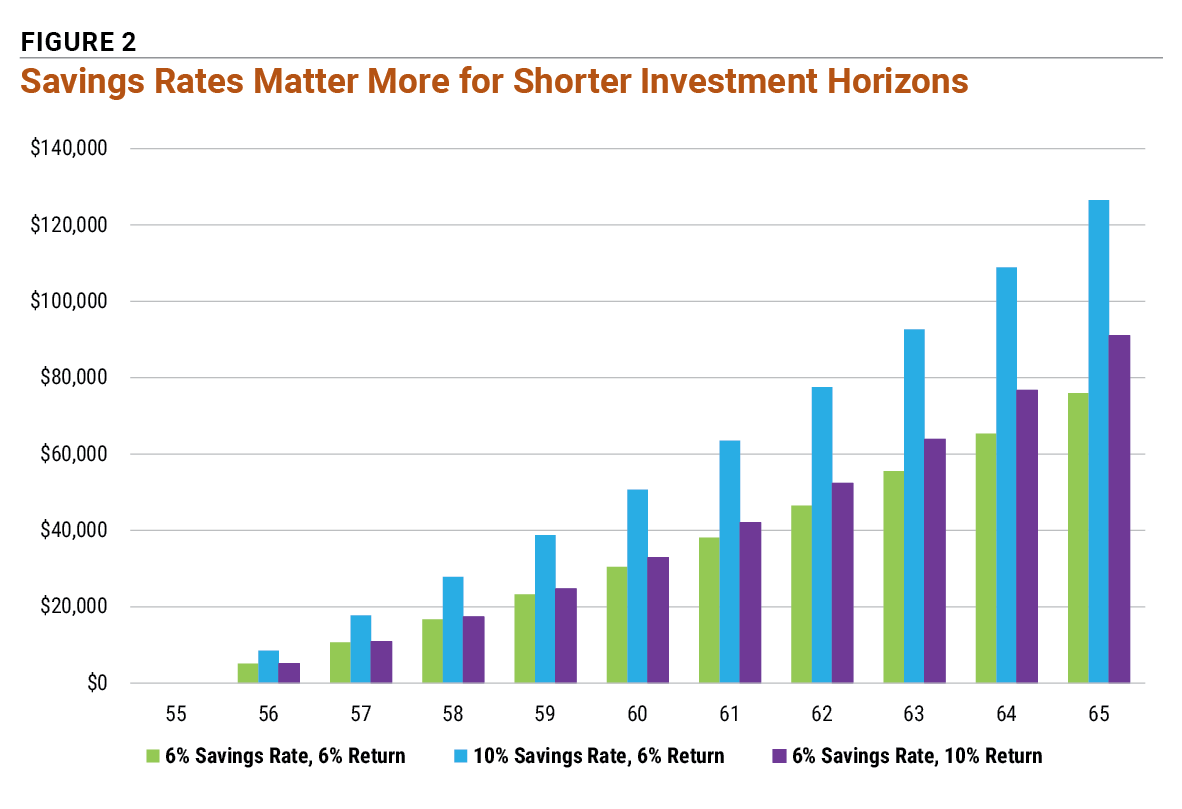
Think of it this way: If the investor’s retirement saving time frame is reduced from 40 years to 20 years—as is the case for a 45-year-old who is just now starting to invest—the shorter time frame reduces the beneficial impact of compounding. The dramatic compounding-based growth in a portfolio really starts to pick up steam after 20 to 25 years. Thus, with a shorter period to work with, a portfolio is benefited more by the direct contributions made to it.
Plus, when “juicing” a portfolio to crank out higher returns, the downside risk is significantly larger in any given year.
For example, over the past 50 years (1976–2025), a portfolio designed to generate a 6% average annualized return had a worst-case one-year return of –4.57%. (This is based on an asset allocation of 55% cash, 30% bonds, 5% large-cap U.S. stocks, and 2.5% each in small-cap U.S. stocks, non-U.S. stocks, real estate and commodities.) This negative return occurred in 2022. There were three other smaller annual losses: –3.60% in 2008, –0.58% in 2015, and –0.22% in 2018.
Conversely, a portfolio that generated a 10% annualized return over the same 50-year span had a worst-case one-year return of –23.45%. (This is based on an asset allocation of 25% to large-cap U.S. stocks, 15% to small-cap U.S. stocks, 10% to non-U.S. stocks, 25% to bonds, 10% to cash, 10% to real estate and 5% to commodities.) This multiasset portfolio was rebalanced annually. There were six other annual losses; the second-largest loss was –13.39% in 2022.
The point here is simple: A portfolio designed to have a higher return is also a higher-risk portfolio. Older investors are not keen on taking large losses inasmuch as they have fewer years in which to recover from such drops in portfolio value. And that’s not to mention the emotional toll that large portfolio losses inflict on investors.
Starting to Save for Retirement at Age 55
For the investor who started saving for retirement at age 55, raising the savings rate from 6% to 10% increased the ending account value by over $50,000 (from $75,937 to $126,562). By contrast, if the portfolio return was increased from 6% to 10%, the ending balance increased by only $15,073 (from $75,937 to $91,010).
This is an investor who started a bit late. Ours is not to judge why they are late, but rather to encourage them to do all they can in preparation for retirement. As clearly demonstrated by this analysis, one thing must happen: The 55-year-old should focus on saving more of their income rather than cranking up the portfolio risk in an attempt to make up for lost time (Figure 2). To be more specific, a 55-year-old who is just starting to build their retirement portfolio will likely need to save more than 10% of their income to hit any sort of reasonable nest egg target value.
The practical outcome of these findings is actually quite helpful. Older investors should save more rather than build aggressive portfolios that expose them to the risk of large losses in any given year. Large losses can emotionally undermine older investors, who naturally have less time to recover from them. A loss of 50% requires a gain of 100% to break even.
Moreover, contributions are an investing variable that is more in the control of the investor, while portfolio performance, particularly in the short run, is less controllable. As a result, investors who rely upon the performance of their portfolios to do the heavy lifting—that is, to make up for their insufficient contributions during their working years—will usually fall into the trap of having too much equity exposure and therefore be exposed to too much risk of loss.
It is my opinion that the performance, or return, of an investment portfolio should accomplish two primary goals: preserve and protect the contributions of the investor, and provide a modest rate of return.
Saving More Now Is the Best Strategy
In an era of “super-sized” meals, drinks, vehicles, houses and egos, the notion of a modest rate of return may sound rather unsophisticated. Nevertheless, I suggest that the performance of a portfolio should not be expected to make up for under-saving on the part of the investor. It is our job as investors to adequately contribute to our retirement investment accounts. An annual contribution rate of 2% to 3% of our income into our 401(k) account or individual retirement account (IRA) is simply inadequate. I suspect we all know that. But perhaps we allow a long list of wants to put the squeeze on our retirement savings rate.
This reminds me of the Fram oil filter commercial slogan from many years ago: “You can pay me now, or pay me later.” The implication of that advertisement was that the cost of a car repair later would be much higher than the cost of proper maintenance now. Similarly, an inadequate savings rate now will require a much higher savings rate later to hit the same nest egg goal.
Consider a simplistic, but illustrative, example: Emily, a 25-year-old worker, begins her career earning $35,000 per year. Her salary increases 3% annually over the next 40 years. If she invests 10% of her income into a 401(k) each year—a rate that could represent a 10% savings rate by her alone or a 6% savings rate by her and a 4% match from her employer, or some other split—she will have a nominal balance of $263,904 accumulated by age 65, assuming a 0% portfolio rate of return. Emily has over one-quarter of $1 million entirely as a result of her own contributions—representing the first engine of growth.
Now, let’s consider the second engine of growth: portfolio performance. If Emily’s 401(k) account averages an annualized return of 6% per year, her account value at age 65 will be $819,429, of which $263,904 represents her contributions. Clearly the portfolio return produces a significant portion of the ending account value, but there’s no growth without contributions!
What if Emily only invests 2% of her salary each year until she retires at age 65? Assuming a 0% return in her retirement portfolio, she will have an account balance of $52,781. Assuming a 6% average annualized return over 40 years, her balance will only be $163,886. To achieve an ending balance of around $819,000 at age 65 while maintaining her low 2% contribution rate, Emily’s retirement portfolio will need to generate an average annualized return of 12.6%. In other words, her inadequate contributions force the portfolio to do the heavy lifting.
Can a portfolio reasonably be expected to produce an average annualized return of 12.6% over a 40-year period? Over the past 100 years, there have been 61 rolling 40-year periods. The S&P 500 index has never produced a 40-year annualized return of 12.6% or more. (The highest 40-year return was 12.5% from January 1, 1950, to December 31, 1989.) This is the performance of a 100% equity retirement portfolio, which is far more volatile than many investors can stomach. In case you’re curious, the average rolling 40-year return for the S&P 500 from 1926 to 2025 was 11.0%.
A more reasonable asset allocation for many investors might be a 60% stock/40% bond portfolio comprising 40% large-cap U.S. stocks, 20% small-cap U.S. stocks, 30% U.S. bonds and 10% cash. Never once has a 60% stock/40% bond portfolio produced a 40-year annualized return of 12.6% or higher since 1926. In fact, over the 61 40-year periods since 1926, the average 40-year rolling return for such a portfolio was 9.8%.
If 25-year-old Emily wanted to achieve this target retirement account balance of $819,429 by age 65 and could earn an average portfolio return of 9.8% (the historical average for a 60% stock/40% bond portfolio), she would need to more than double her annual savings rate from 2.0% to 4.1%. If her retirement target was adjusted to $1 million by age 65 (and her portfolio still averaged a 9.8% return), she would need to save 5% each year. If her target was adjusted to $2 million, she would need to save 10% each year.
You might be interested to know that the 60% stock/40% bond portfolio’s most recent 40-year return (for the period from 1986 to 2025) was 8.8%, or more than 100 basis points (bps) below the overall average 40-year return. This suggests that investors may need to save even more if their most recent portfolio performance falls below the overall average performance.
This type of analysis can go on forever. It need not. The analysis presented here sufficiently illustrates a glaring reality: A 2% savings rate will not get the job done to be adequately prepared for retirement. Nor is a 4% savings rate likely to be adequate.
This may seem very discouraging to someone who is doing their best to commit 4% or 5% of their income each year into their retirement portfolio. Don’t be discouraged. If 4% is your best effort right now, take courage in that. However, work toward a 6% savings rate or higher—with 10% or more being an ideal goal. As with many goals, we work our way there over time.
Go In-Depth on Retirement With Israelsen
A live AAII Retirement Workshop with Craig Israelsen, Ph.D., was recorded in September, but you can still get everything it covered. Access all three on-demand recordings (about 1.5 hours each) covering portfolio redundancy, true diversification and safe withdrawal strategies, plus the full presentation slides, all for just $99. Click here to learn more.
Related
Beginning Investor
How to Start Saving for Retirement
Related
PRISM Wealth-Building Process
A One-Page Wealth-Building Plan to Reach the Goal of Retirement
Discussion
FREE REPORT

Get your free copy of our special
report analyzing the tech stocks
most likely to outperform the
market.
No comments have been added yet. Add your thoughts to the discussion!
You need to log in as a registered AAII user before commenting.
Log InCreate an account